
[ad_1]
District 5 (D5) has long carried the reputation as Singapore’s “education belt”, anchored by NUS and a network of higher education institutions such as INSEAD and ESSEC. But in recent years, the district has evolved beyond its academic roots. The transformation of One North into a thriving tech and media hub has drawn a new generation of professionals and investors, pushing D5 into a different territory: it now appeals equally to homeowners and landlords.
In our previous analysis, we examined how one- and two-bedroom units here performed across different project ages, and what that revealed about lease decay and long-term value. This time, we turn our attention to the larger segments.
How do three- and four-bedroom units in D5 stack up, and does age still play a defining role in their performance?
For consistency, we’ll use the same criteria as the earlier half of our study: newer condos refer to projects with leases starting from 1994 to 2014, and older condos are those from 1993 and earlier. All data is based solely on resale and sub sale transactions, to avoid the effects of new launch discounts or developer pricing strategies.
As before, note that Parc Clematis played a major role in lifting D5’s overall performance after 2019, thanks to its large scale and affordable launch pricing. We also continue to group projects by lease start year rather than TOP year, which is why developments such as Dover Parkview and Heritage View (completed later but with leases starting in 1996) fall under the “older” category.
So if you’ve been analysing D5 and wondering whether size changes the story, it might be worth looking beyond averages. Larger units tend to behave differently, especially when family demand and rental yields overlap. Tell us what you’re planning and we’ll connect you with one of our trusted partner agents who can help you see how the trends differ once you move from compact to family-sized homes.
With that in mind, let’s see whether age still matters when we move up to the larger three- and four-bedder units in D5.
3-bedroom units
Average $PSF
| Year | New | Old | Difference |
| 2014 | $1,087 | $989 | $99 |
| 2015 | $1,105 | $871 | $234 |
| 2016 | $1,054 | $875 | $179 |
| 2017 | $1,057 | $855 | $202 |
| 2018 | $1,117 | $1,000 | $118 |
| 2019 | $1,132 | $1,016 | $116 |
| 2020 | $1,168 | $962 | $205 |
| 2021 | $1,282 | $1,048 | $234 |
| 2022 | $1,423 | $1,149 | $274 |
| 2023 | $1,508 | $1,238 | $270 |
| 2024 | $1,545 | $1,315 | $230 |
| Annualised | 3.58% | 2.90% |
Over the past decade, newer three-bedders in D5 saw a higher annualised growth rate in $PSF. The $PSF gap between old and new has also widened slightly over the decade, from around $99 in 2014 to $230 in 2024.
However, we also need to look at quantum (overall price) and not just $PSF:
Average price
| Year | New | Old | Difference |
| 2014 | $1,541,692 | $1,281,750 | $259,942 |
| 2015 | $1,501,833 | $1,188,353 | $313,480 |
| 2016 | $1,432,409 | $1,160,410 | $271,998 |
| 2017 | $1,366,982 | $1,146,594 | $220,388 |
| 2018 | $1,474,398 | $1,195,278 | $279,121 |
| 2019 | $1,451,335 | $1,296,313 | $155,023 |
| 2020 | $1,542,354 | $1,241,805 | $300,549 |
| 2021 | $1,653,607 | $1,345,144 | $308,463 |
| 2022 | $1,855,016 | $1,461,579 | $393,437 |
| 2023 | $1,945,353 | $1,582,044 | $363,308 |
| 2024 | $1,994,048 | $1,614,156 | $379,892 |
| % increase from 2014 to 2024 | 29.34% | 25.93% |
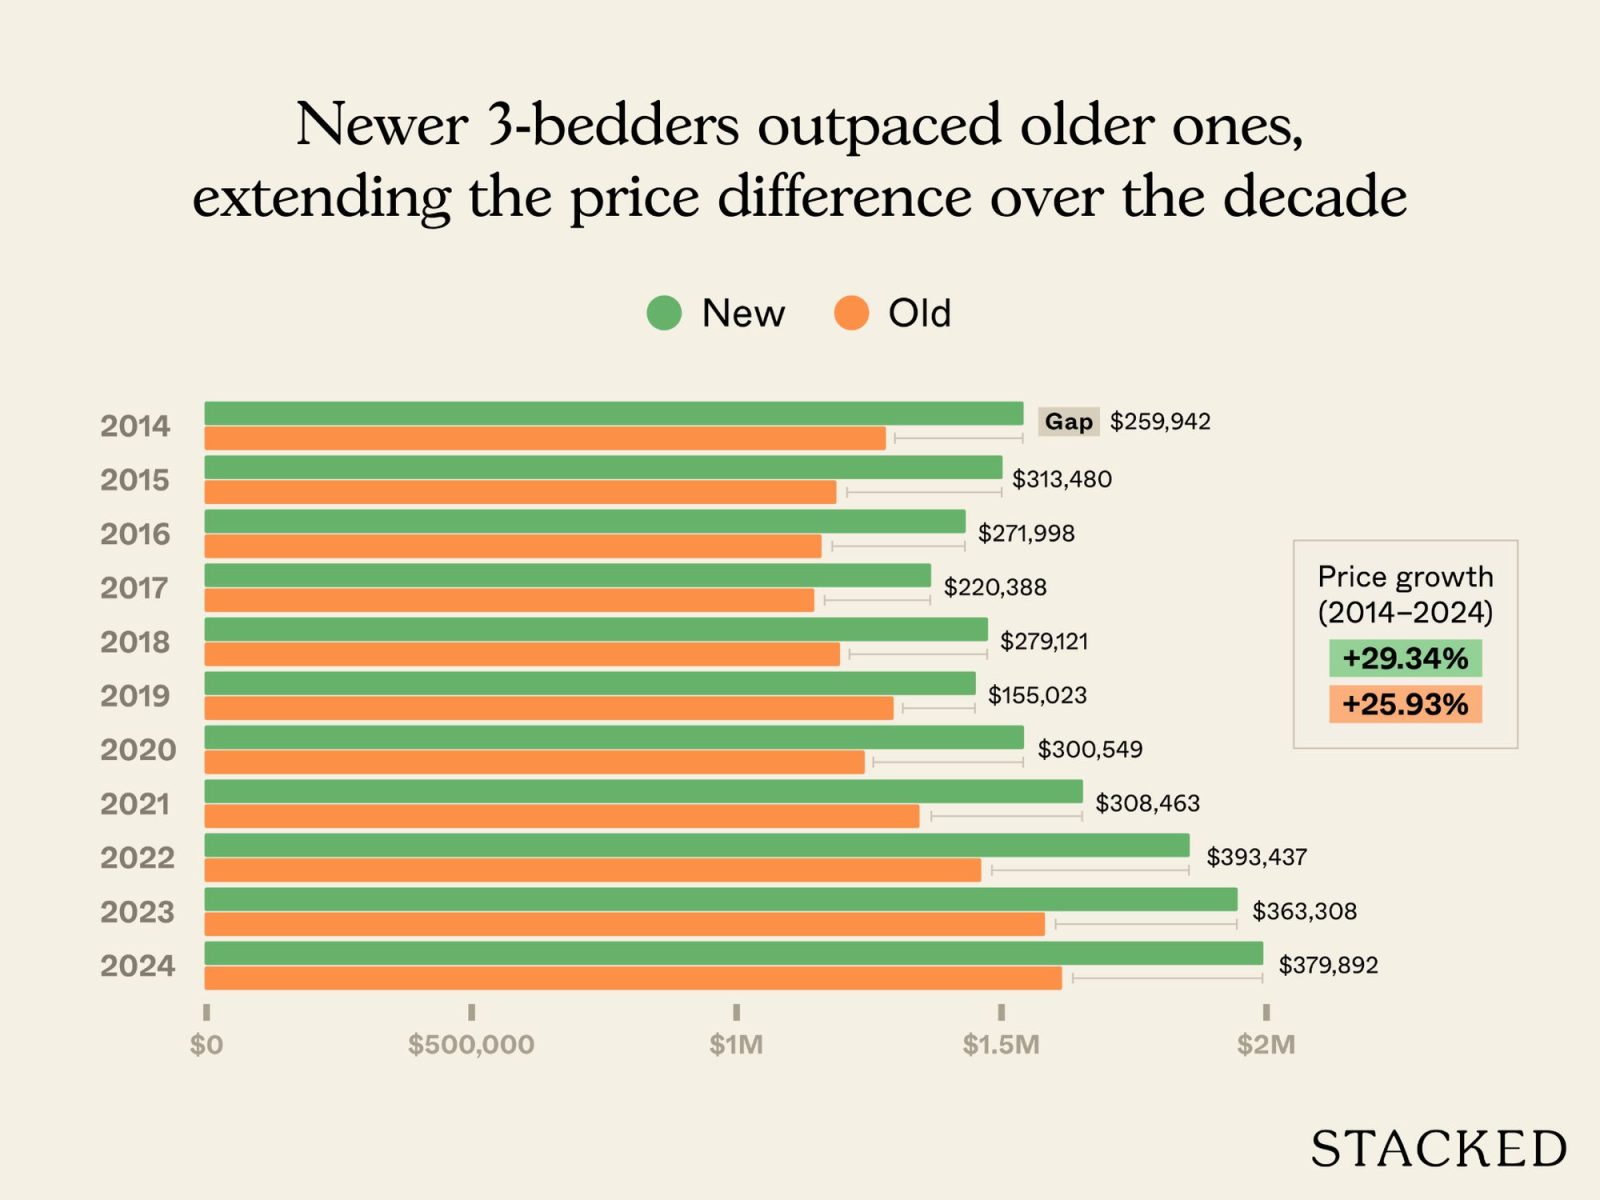
The performance between the two is quite close, which is surprising, as you might expect lease decay to have a deeper impact on the 20+ year old projects.
The gap between new and old units has widened slightly over the decade, from about $260,000 in 2014 to nearly $380,000 in 2024. Spaciousness might explain this, so let’s look at the unit sizes:
Average size (based on units transacted)
| Year | New | Old |
| 2014 | 1434 | 1325 |
| 2015 | 1363 | 1394 |
| 2016 | 1362 | 1345 |
| 2017 | 1290 | 1364 |
| 2018 | 1316 | 1198 |
| 2019 | 1296 | 1284 |
| 2020 | 1332 | 1291 |
| 2021 | 1306 | 1285 |
| 2022 | 1315 | 1276 |
| 2023 | 1306 | 1284 |
| 2024 | 1312 | 1230 |
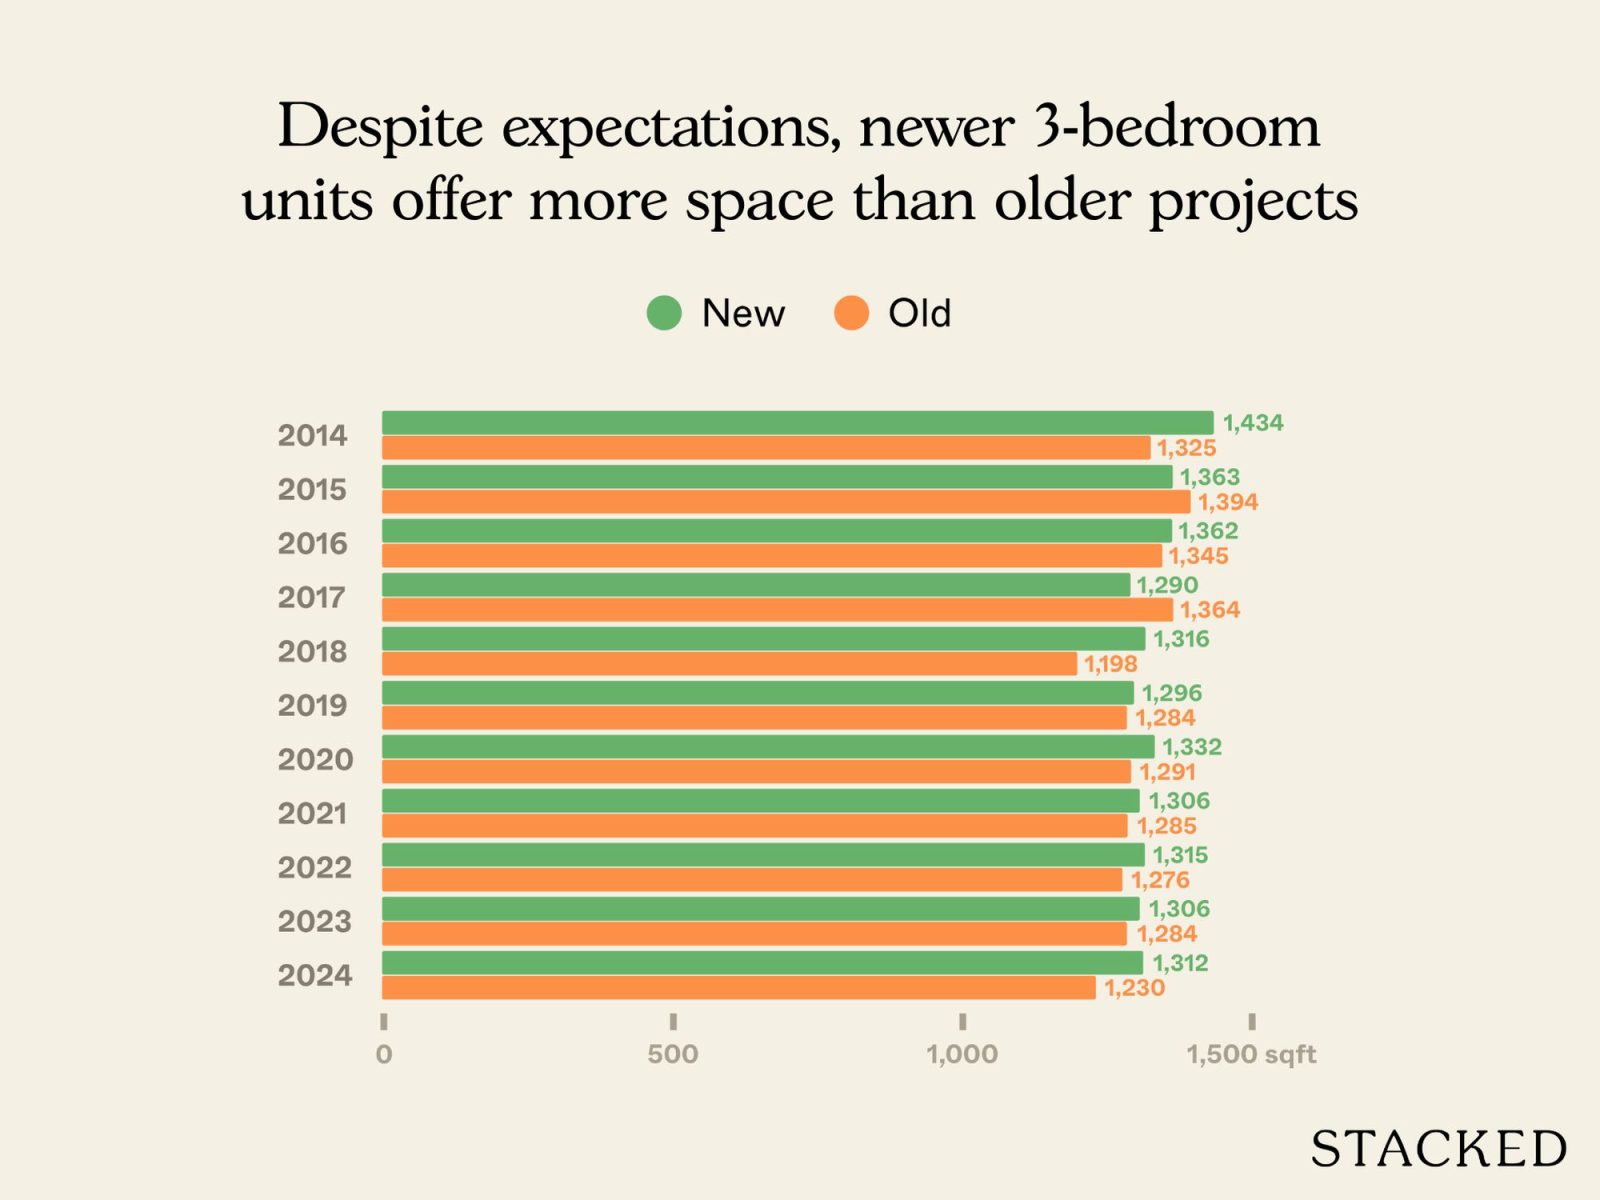
This is also an unexpected result. In most cases, we would expect older projects to have larger average sizes, but we can see that in recent years, it’s the newer three-bedders that have been larger.
For buyers, it may be worth noting that in D5, the older projects aren’t consistently the bigger ones.
These are the total number of three-bedder transactions we looked at:
No. of transactions
| Year | New | Old |
| 2014 | 49 | 20 |
| 2015 | 74 | 17 |
| 2016 | 56 | 29 |
| 2017 | 84 | 32 |
| 2018 | 84 | 18 |
| 2019 | 68 | 16 |
| 2020 | 76 | 17 |
| 2021 | 142 | 20 |
| 2022 | 107 | 19 |
| 2023 | 86 | 20 |
| 2024 | 96 | 18 |
The transaction numbers on both sides are decent and enough to be representative.
Now let’s look at the specific projects that were transacted in 2024:
New (sorted by price low to high)
| Project | Average $PSF | Average price | Average size | No. of units sold | Lease start year |
| WESTCOVE CONDOMINIUM | $1,099 | $1,437,329 | 1314 | 6 | 1995 |
| FABER CREST | $1,247 | $1,575,076 | 1264 | 9 | 1996 |
| BLUE HORIZON | $1,417 | $1,640,984 | 1158 | 7 | 2000 |
| WATERFRONT @ FABER | $1,551 | $1,643,833 | 1061 | 6 | 2013 |
| SEAHILL | $1,683 | $1,830,000 | 1087 | 2 | 2011 |
| HERITAGE VIEW | $1,617 | $1,984,389 | 1227 | 20 | 1996 |
| THE TRILINQ | $1,810 | $1,996,639 | 1121 | 20 | 2012 |
| THE VISION | $1,556 | $2,043,333 | 1313 | 3 | 2008 |
| CLEMENTIWOODS CONDOMINIUM | $1,408 | $2,187,500 | 1556 | 4 | 2006 |
| ONE-NORTH RESIDENCES | $1,734 | $2,295,000 | 1324 | 4 | 2005 |
| VARSITY PARK CONDOMINIUM | $1,416 | $2,339,750 | 1674 | 8 | 2004 |
| THE ROCHESTER RESIDENCES | $1,554 | $3,031,500 | 2034 | 7 | 2005 |
Old (sorted by price low to high)
| Project | Average $PSF | Average price | Average size | No. of units sold | Lease start year |
| WEST BAY CONDOMINIUM | $1,153 | $1,458,633 | 1266 | 6 | 1991 |
| REGENT PARK | $1,391 | $1,633,571 | 1175 | 7 | 1993 |
| DOVER PARKVIEW | $1,405 | $1,773,600 | 1262 | 5 | 1993 |
On average, the older three-bedders tend to be cheaper, as expected, but it’s not entirely clear-cut. While older projects like Dover Parkview and Regent Park still cost less overall, several newer three-bedders overlap in pricing. Westcove Condominium, for instance, is technically a newer project (lease from 1995), yet it recorded the lowest average price and $PSF among the newer group.
This is likely a proximity issue, as Westcove is not near any MRT station, and it demonstrates how factors like this can have a deeper impact than age.
We can also see that The Rochester Residences and One-North Residences sit at the high-end of the scale. This isn’t just about age; Rochester Residences has a commercial component and is next to Star Vista and Buona Vista MRT station (EWL, CCL), while One-North Residences has access to One North MRT (CCL) as well as the amenities of Fusionopolis.
Proximity to transport and retail amenities weigh much more than age, for D5 three-bedders.
Here’s a look at the performance of the above projects over the past decade:
| Year | VARSITY PARK CONDOMINIUM | HERITAGE VIEW | THE VISION | BLUE HORIZON | REGENT PARK | CLEMENTIWOODS CONDOMINIUM | ONE-NORTH RESIDENCES | DOVER PARKVIEW | FABER CREST | THE ROCHESTER RESIDENCES | WEST BAY CONDOMINIUM | WESTCOVE CONDOMINIUM | SEAHILL | THE TRILINQ | WATERFRONT @ FABER |
| 2014 | $1,012 | $1,171 | $1,164 | $1,080 | $1,062 | $1,086 | $1,348 | $1,123 | $1,008 | $1,267 | $953 | $908 | |||
| 2015 | $1,047 | $1,147 | $1,186 | $1,040 | $929 | $1,352 | $1,010 | $831 | $1,339 | $839 | $827 | ||||
| 2016 | $1,030 | $1,108 | $1,180 | $990 | $855 | $1,004 | $1,369 | $998 | $844 | $1,258 | $790 | $767 | |||
| 2017 | $1,072 | $1,113 | $1,176 | $1,005 | $863 | $1,000 | $1,373 | $1,030 | $820 | $1,340 | $791 | $817 | $1,268 | ||
| 2018 | $1,061 | $1,217 | $1,259 | $1,048 | $999 | $966 | $1,495 | $1,185 | $931 | $1,318 | $817 | $842 | $1,346 | $1,341 | |
| 2019 | $1,107 | $1,177 | $1,117 | $1,060 | $983 | $1,013 | $1,510 | $1,115 | $917 | $1,377 | $819 | $829 | $1,363 | $1,463 | |
| 2020 | $1,098 | $1,189 | $1,243 | $1,062 | $1,015 | $1,051 | $1,428 | $1,091 | $896 | $1,283 | $811 | $806 | $1,294 | $1,547 | $1,348 |
| 2021 | $1,121 | $1,262 | $1,296 | $1,134 | $1,019 | $1,130 | $1,486 | $1,198 | $961 | $1,353 | $868 | $942 | $1,417 | $1,527 | $1,404 |
| 2022 | $1,227 | $1,419 | $1,506 | $1,241 | $1,220 | $1,188 | $1,575 | $1,312 | $1,052 | $1,503 | $1,011 | $1,002 | $1,531 | $1,638 | $1,453 |
| 2023 | $1,360 | $1,575 | $1,579 | $1,329 | $1,263 | $1,476 | $1,687 | $1,376 | $1,235 | $1,567 | $1,073 | $1,062 | $1,640 | $1,788 | $1,530 |
| 2024 | $1,416 | $1,617 | $1,556 | $1,417 | $1,391 | $1,408 | $1,734 | $1,405 | $1,247 | $1,554 | $1,153 | $1,099 | $1,683 | $1,810 | $1,551 |
| Annualised (2014 to 2024) | 3.42% | 3.28% | 2.95% | 2.75% | 2.73% | 2.63% | 2.55% | 2.27% | 2.15% | 2.06% | 1.93% | 1.92% | – | – | – |
Some of the projects don’t have transactions in both 2014 and 2024, so we’ve focused on the ones that do.
Over the past decade, three-bedders across D5 show a fairly even mix of outcomes between older and newer projects. Some of the newer ones, such as Varsity Park Condominium and Heritage View, have performed quite well with annualised gains of around 3.4 and 3.3 per cent respectively; but several others like The Vision, Blue Horizon, and One-North Residences hover between 2.5 and 3 per cent, broadly matching the older projects. Among the older group, Dover Parkview and Regent Park hold their ground at roughly 2.3 to 2.7 per cent annualised growth.
Overall, this suggests that age wasn’t a particularly big factor for D5’s three-bedders.
While three-bedders are infrequently bought as rental assets, their yield still offers insight into pricing and rental expectations; so let’s have a look:
| Project | Average price in 2024 | Average monthly rent (June 2024 – June 2025) | Rental yield |
| WATERFRONT @ FABER | $1,643,833 | $3,967 | 2.90% |
| THE TRILINQ | $1,996,639 | $5,497 | 3.30% |
| CLEMENTIWOODS CONDOMINIUM | $2,187,500 | $6,045 | 3.32% |
| REGENT PARK | $1,633,571 | $4,588 | 3.37% |
| VARSITY PARK CONDOMINIUM | $2,339,750 | $6,767 | 3.47% |
| THE ROCHESTER RESIDENCES | $3,031,500 | $8,786 | 3.48% |
| FABER CREST | $1,575,076 | $4,601 | 3.51% |
| THE VISION | $2,043,333 | $6,062 | 3.56% |
| HERITAGE VIEW | $1,984,389 | $5,993 | 3.62% |
| ONE-NORTH RESIDENCES | $2,295,000 | $6,939 | 3.63% |
| DOVER PARKVIEW | $1,773,600 | $5,568 | 3.77% |
| SEAHILL | $1,830,000 | $6,045 | 3.96% |
| BLUE HORIZON | $1,640,984 | $5,500 | 4.02% |
| WESTCOVE CONDOMINIUM | $1,437,329 | $4,835 | 4.04% |
| WEST BAY CONDOMINIUM | $1,458,633 | $4,960 | 4.08% |
Unsurprisingly, the highest yields come from projects with the lowest prices, as gross rental yield = (annual rental income/total price).
West Bay Condominium, an older development, tops the list at just over four per cent, followed closely by Westcove Condominium, a newer but competitively priced project.
Among the mid-range performers, Dover Parkview and Blue Horizon sit comfortably in the 3.7 to four per cent range. We would consider this impressive for family-sized units, which often see yields at three per cent or lower due to their higher quantum. D5’s status as an education belt, plus the growing strength of One North, contributes to steady tenant demand.
We can also see it in how The Rochester Residences, Varsity Park Condominium, and One-North Residences still manage healthy yields of around 3.5 to 3.6 per cent despite their higher price points.
4-bedroom units
Average $PSF
| Year | New | Old | Difference |
| 2014 | $1,032 | ||
| 2015 | $1,040 | ||
| 2016 | $907 | ||
| 2017 | $980 | ||
| 2018 | $1,040 | ||
| 2019 | $1,120 | ||
| 2020 | $1,101 | ||
| 2021 | $1,250 | $1,205 | $45 |
| 2022 | $1,295 | $1,378 | -$83 |
| 2023 | $1,407 | $1,197 | $210 |
| 2024 | $1,450 | ||
| Annualised (2021 to 2023) | 6.11% | -0.33% |
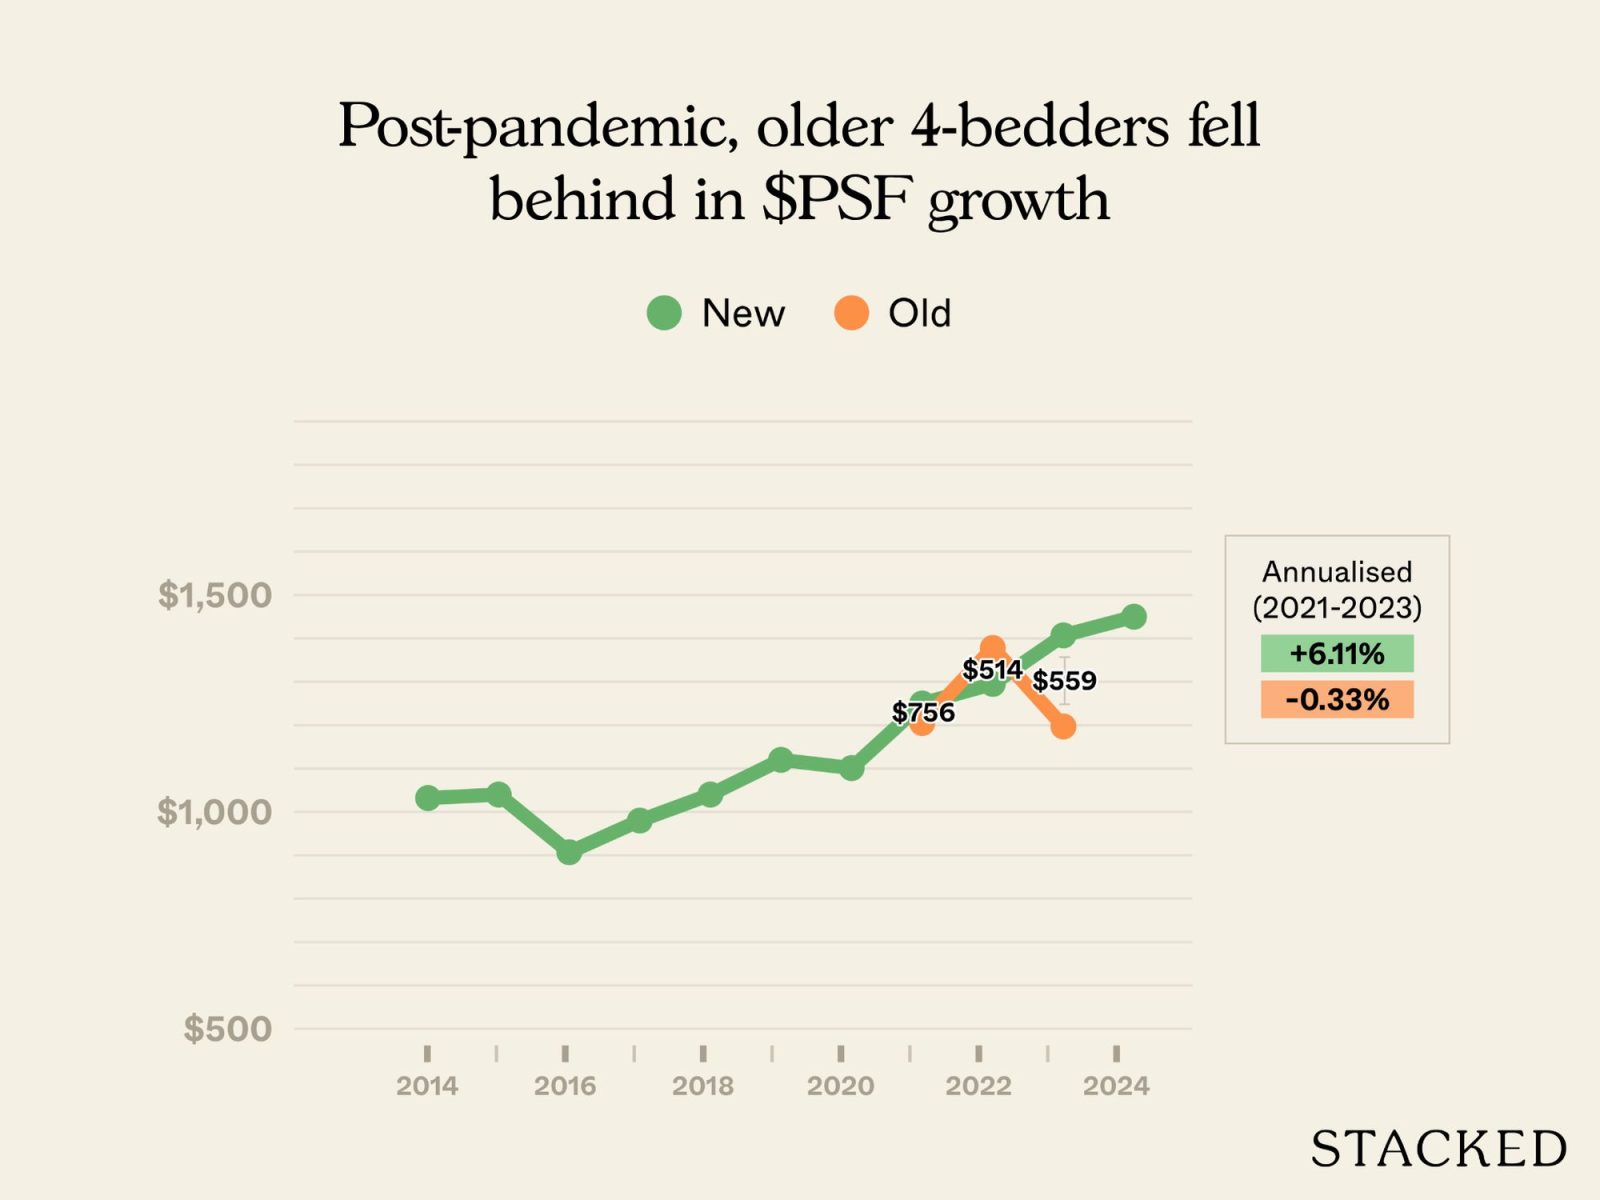
Here we run into a common issue with four-bedders. These very large, very high cost units are much fewer in number, and transactions tend to be limited.
Still, going by the few transactions we have, it appears that newer four-bedders pulled far ahead in $PSF, whilst older four-bedders saw stagnant prices. But this is a very small number of transactions, and it’s important to look at actual average prices too:
Average price
| Year | New | Old | Difference |
| 2014 | $1,927,545 | ||
| 2015 | $1,859,425 | ||
| 2016 | $1,755,625 | ||
| 2017 | $1,780,617 | ||
| 2018 | $1,948,059 | ||
| 2019 | $2,548,951 | ||
| 2020 | $2,324,308 | ||
| 2021 | $2,558,384 | $2,685,000 | -$126,616 |
| 2022 | $2,493,722 | $2,730,000 | -$236,278 |
| 2023 | $2,515,350 | $2,668,000 | -$152,650 |
| 2024 | $2,653,608 | ||
| % increase from 2021 to 2023 | -1.68% | -0.63% |
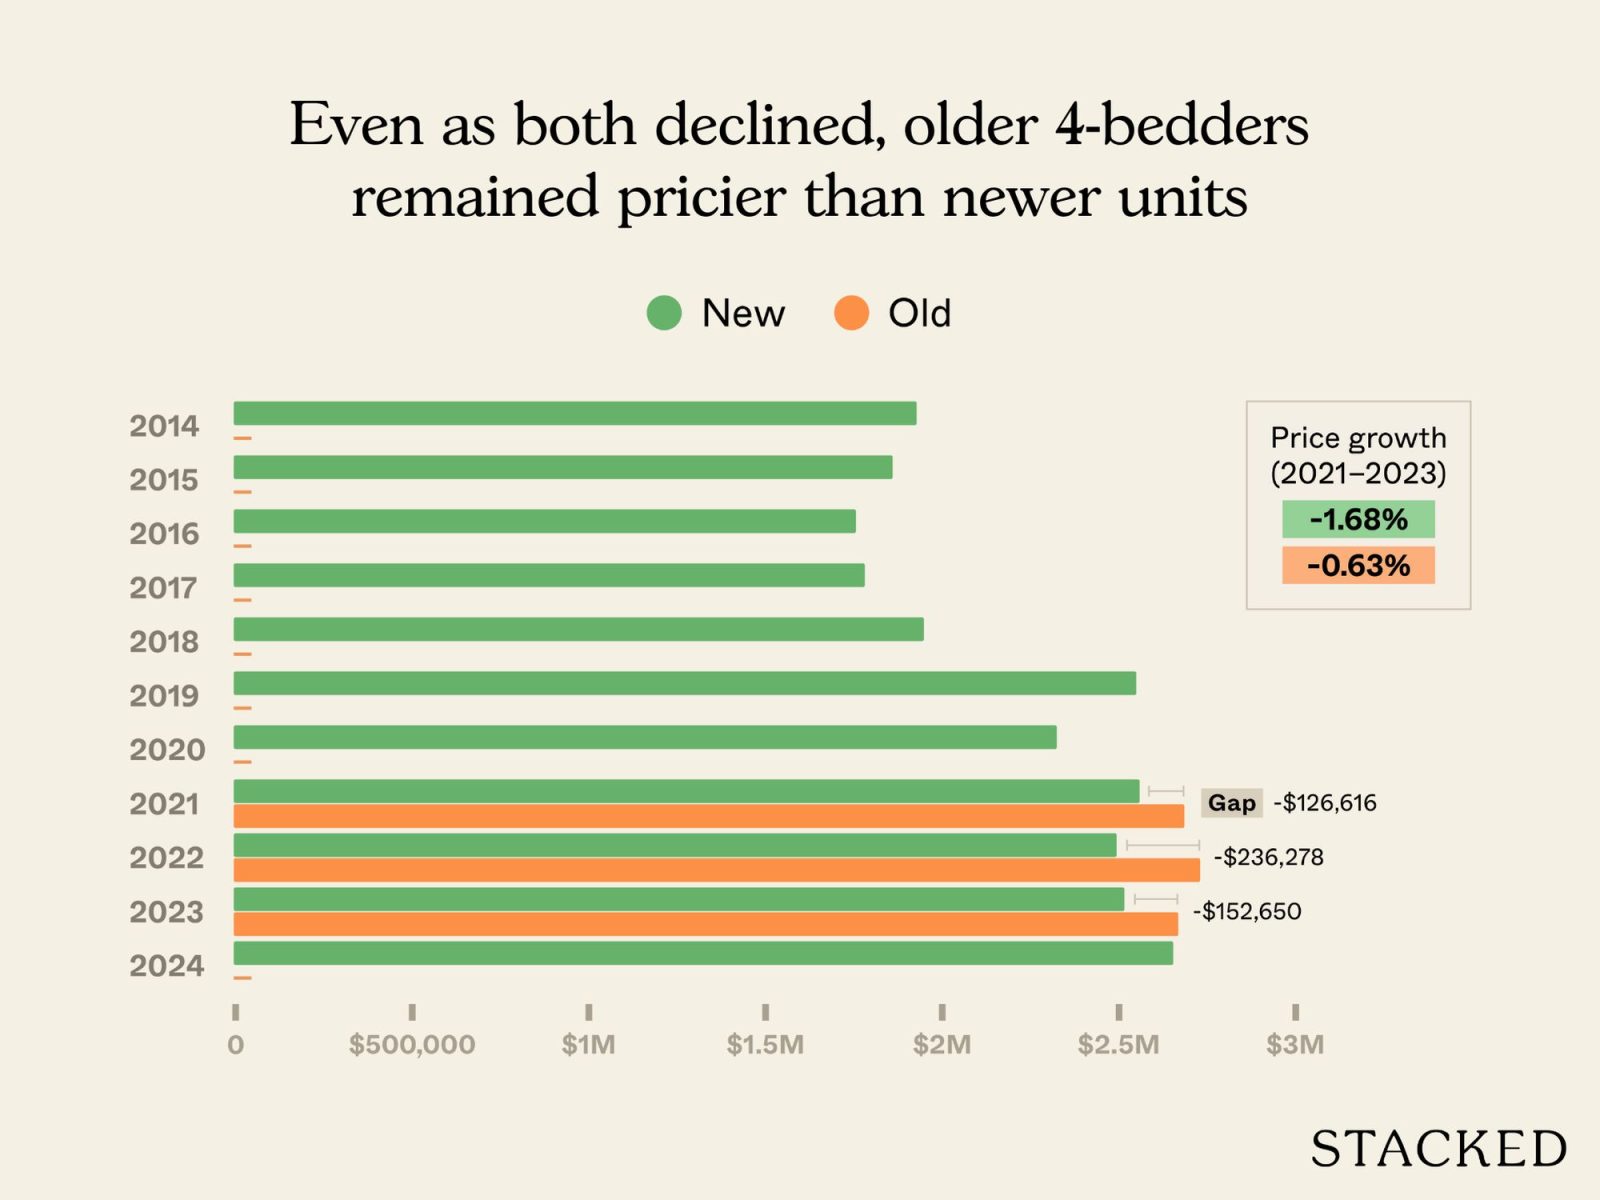
Both newer and older four-bedders in D5 saw a slight dip in quantum, though it was worse for newer four-bedders than older ones. This is likely due to older four-bedders being much larger, so let’s have a look at their sizes:
Average size (based on units transacted)
| Year | New | Old |
| 2014 | 1854 | |
| 2015 | 1804 | |
| 2016 | 1927 | |
| 2017 | 1827 | |
| 2018 | 1890 | |
| 2019 | 2285 | |
| 2020 | 2148 | |
| 2021 | 2074 | 2228 |
| 2022 | 1961 | 1981 |
| 2023 | 1898 | 2228 |
| 2024 | 1936 |
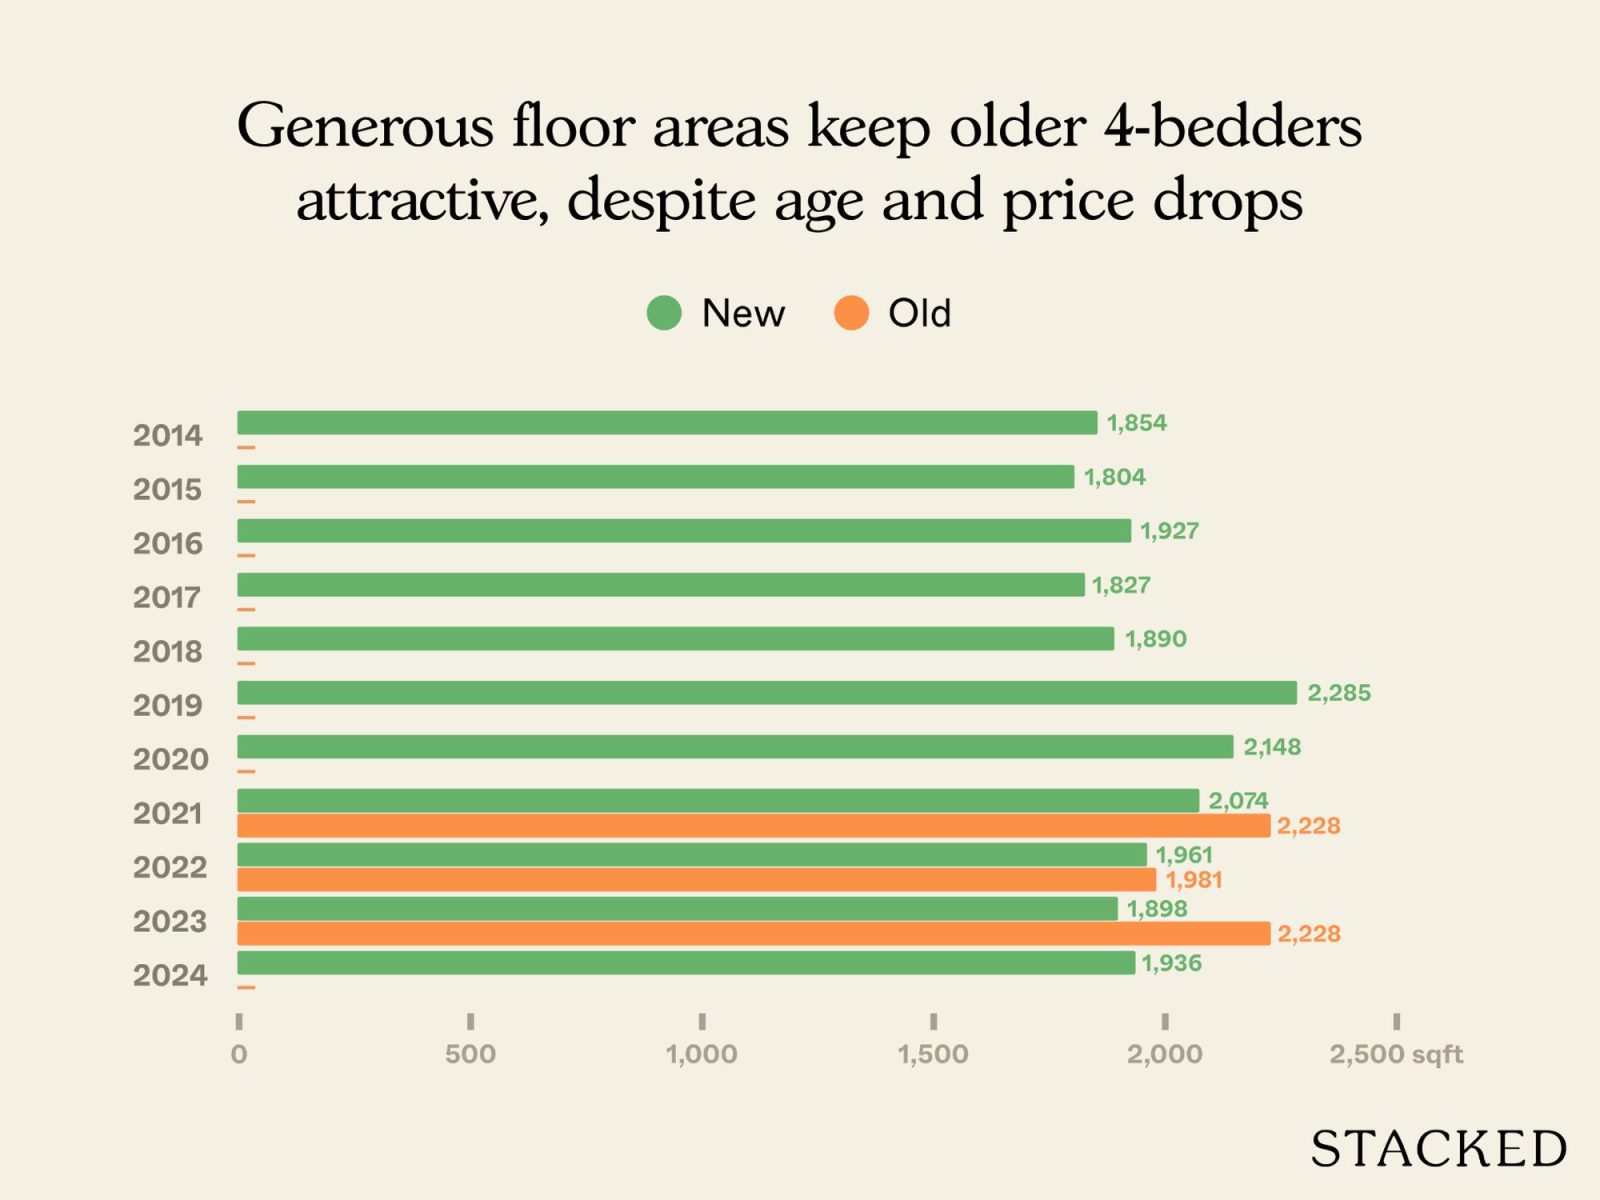
As expected, the older four-bedders are generally larger. This explains their higher average prices, and lower $PSF compared to newer counterparts.
Unfortunately, the number of transactions remains too low to draw many conclusions from this:
No. of transactions
| Year | New | Old |
| 2014 | 11 | |
| 2015 | 16 | |
| 2016 | 8 | |
| 2017 | 12 | |
| 2018 | 15 | |
| 2019 | 9 | |
| 2020 | 13 | |
| 2021 | 31 | 1 |
| 2022 | 22 | 1 |
| 2023 | 20 | 1 |
| 2024 | 21 |
Since older projects did not have any transactions in 2024, we will only look at projects with transactions in 2023
New (sorted by price low to high)
| Project | Average $PSF | Average price | Average size | No. of units sold | Lease start year |
| WATERFRONT @ FABER | $1,495 | $1,951,600 | 1307 | 5 | 2013 |
| FABER CREST | $1,157 | $2,077,500 | 1798 | 2 | 1996 |
| VARSITY PARK CONDOMINIUM | $1,404 | $2,330,000 | 1663 | 2 | 2004 |
| CLEMENTIWOODS CONDOMINIUM | $1,336 | $2,334,000 | 1755 | 2 | 2006 |
| THE VISION | $1,576 | $2,528,000 | 1604 | 1 | 2008 |
| THE TRILINQ | $1,413 | $3,067,250 | 2423 | 8 | 2012 |
Old
| Project | Average $PSF | Average price | Average size | No. of units sold | Lease start year |
| DOVER PARKVIEW | $1,197 | $2,668,000 | 2228 | 1 | 1993 |
In 2023, only a single older project, Dover Parkview, recorded a sale. Its average price of about $2.67 million puts it roughly in the middle of the range compared to newer four-bedders (around $1.95 million at Waterfront @ Faber to over $3 million at The Trilinq). Unfortunately, the comparison isn’t too meaningful, given the single data point.
Among the newer group, The Trilinq posted the highest average price, largely because its four-bedder was the largest at over 2,400 sq ft.
Let’s look at the performances of these projects over the past decade
| Year | VARSITY PARK CONDOMINIUM | CLEMENTIWOODS CONDOMINIUM | FABER CREST | THE VISION | WATERFRONT @ FABER | THE TRILINQ | DOVER PARKVIEW |
| 2014 | $849 | $1,006 | $887 | ||||
| 2015 | $1,010 | $1,007 | $807 | $1,189 | |||
| 2016 | $1,036 | $993 | $801 | ||||
| 2017 | $1,109 | $1,011 | $817 | $1,222 | |||
| 2018 | $1,086 | $1,038 | $842 | $1,143 | $1,070 | ||
| 2019 | $1,178 | $1,129 | $946 | $1,080 | |||
| 2020 | $994 | $935 | 1362 | $1,215 | |||
| 2021 | $1,067 | $1,085 | $954 | $1,370 | 1401 | $1,351 | $1,205 |
| 2022 | $1,247 | $1,315 | $1,029 | 1449 | $1,343 | $1,378 | |
| 2023 | $1,404 | $1,336 | $1,157 | $1,576 | 1494.6 | $1,413 | $1,197 |
| 2024 | $1,452 | $1,209 | $1,621 | 1474.5 | $1,379 | ||
| Annualised (2021 to 2023) | 14.71% | 10.94% | 10.12% | 7.26% | 3.29% | 2.24% | -0.33% |
Since we’re basing this on a very short and volatile period (the aftermath of COVID from 2021 to 2023), these results should be read with caution.
Most of the newer four-bedders recorded rapid price growth, ranging from about two to nearly 15 per cent annualised; Varsity Park Condominium, Clementiwoods Condominium, and Faber Crest in particular saw double-digit annualised gains.
As most market watchers will tell you though, nearly every property saw good gains in 2021 to 2023, as there was a post-Covid housing supply crunch; so what we see above isn’t unique to D5 or its four-bedders.
Dover Parkview, the only older project in this dataset, showed a slight dip; but there isn’t much to be drawn from this single data point.
It’s uncommon that units the size of four-bedders are bought to be rented out, but let’s have a look for completeness
| Project | Average price in 2023 | Average monthly rent (June 2024 – June 2025) | Rental yield |
| THE TRILINQ | $3,067,250 | $7,013 | 2.74% |
| DOVER PARKVIEW | $2,668,000 | $6,900 | 3.10% |
| FABER CREST | $2,077,500 | $5,458 | 3.15% |
| THE VISION | $2,528,000 | $7,083 | 3.36% |
| WATERFRONT @ FABER | $1,951,600 | $5,750 | 3.54% |
| CLEMENTIWOODS CONDOMINIUM | $2,334,000 | $7,543 | 3.88% |
| VARSITY PARK CONDOMINIUM | $2,330,000 | $8,019 | 4.13% |
Rather impressively, almost all the projects here maintain gross yields above three per cent and even creep over four per cent (for Varsity Park). This is despite the high quantum of the units involved.
Varsity Park Condominium, by the way, is well known for seeing strong tenant demand from NUS staff, students, and expatriate families in the West Coast area. As the name implies, it’s a good place to stay if you need access to the university.
Notably, Dover Parkview still manages a respectable rental yield of around 3.1 per cent, not far behind several newer counterparts.
Conclusion:
Overall, age doesn’t seem to have impacted D5’s three- and four-bedders too much. While newer projects do show stronger price growth in $PSF terms, older developments continue to hold their ground: that’s both in terms of overall quantum and rental returns.
This balance may reflect D5’s unique qualities: proximity to institutions like NUS, One-North, and major business parks can mitigate the age factor.
For three-bedders, the difference between old and new remains modest: newer projects such as Heritage View and Varsity Park Condominium have grown at roughly three per cent annualised, only slightly ahead of long-standing developments like Dover Parkview and Regent Park. Buyers in this district should consider amenities and MRT access over concerns of age.
Four-bedders, on the other hand, are far harder to assess. Transaction volumes are low, and the data is too sparse to draw reliable conclusions.
Ultimately, D5 continues to be one of Singapore’s most in-demand districts: whether you’re an upgrader or an investor eyeing yields, D5 seems to have something to offer. But from what we see above, don’t expect the older projects here to come with more affordable price points; they’re holding their own even past 20 years of age.
Follow us on Stacked Pro, as we continue to explore the effect of the age gap in various districts. If you’d like to get in touch for a more in-depth consultation, you can do so here.
The post We Compared Old vs New Condos in One of Singapore’s Fastest-Growing Districts — Here’s What We Found for Family-Sized Units appeared first on Property Blog Singapore – Stacked Homes.
[ad_2]
Source link –
Leave a Reply